A clean roof, a cleared gutter, a photo: photo verification for insurer home maintenance rewards
Property insurers can cut water and storm claims by rewarding maintenance. How photo verification rules make home maintenance rewards workable when the only proof is a photo.
Blocked gutters cause water ingress. Moss on a roof holds moisture and lifts tiles. A boiler that skips its annual service fails in January. Property insurers pay for all of this and, historically, could do nothing about it except raise premiums after the fact.
A maintenance rewards program changes the timing. The insurer pays a small reward for a maintenance action before the season that produces the claim: gutters cleared in autumn, roof inspected in spring, boiler serviced before winter, smoke detectors tested and photographed. The policyholder gets a reward and a nudge. The insurer gets fewer claims and a customer relationship that is not built entirely on bad news.
The motor version of this, rewarding a winter tyre change, is mostly a document verification problem, because a garage invoice proves the work. Home maintenance is harder. Much of it is done by the homeowner, and the only evidence is a photo of a gutter.
What can a photo actually prove?
Less than people hope and more than sceptics assume. It is worth being precise.
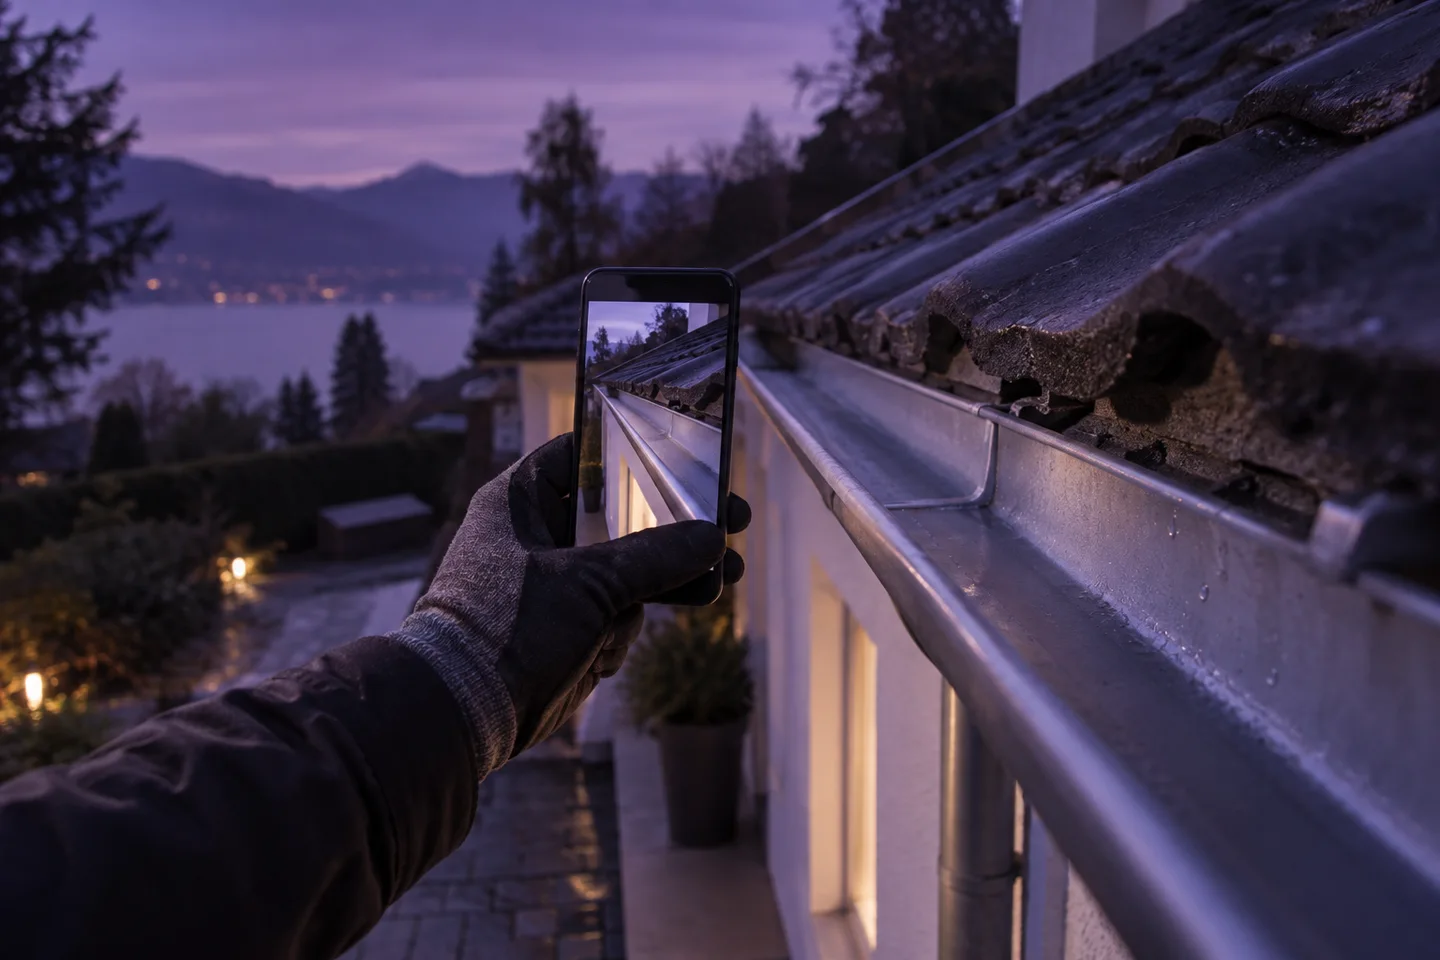
A photo of a gutter can show that a gutter is visible, that it appears free of leaves and debris, that the downpipe is clear at the top, and that the image was taken outdoors in daylight. It cannot prove which house it is, that it was taken today, or that the whole run of guttering looks the same. A photo of a roof can show tiles free of moss and no visibly displaced tiles. It cannot prove structural soundness.
So the program has to be designed around what the evidence can carry. The right pattern for homeowner-performed maintenance is a before-and-after pair plus a receipt or a contractor invoice where one exists. Where a professional did the work, the invoice does most of the proving and the photo confirms it. Where the homeowner did it, the photo pair is the evidence and the reward is scaled to what a photo pair can support.
The checks, concretely
Photo quality gate. Blurry, dark, or badly framed photos are rejected at capture with an instruction to retake. This matters more for outdoor maintenance photos than for receipts, because a dark photo of a roof is worthless and a policyholder who hears nothing for two days will not try again.
Yes-or-no questions of the image. Is a gutter visible? Is it free of visible debris? Is the downpipe opening clear? Is this an exterior daytime photo? Each question is answered with a confidence score. The program’s standard is expressed as which questions must be yes. Low-confidence answers route to a reviewer.
Before-and-after comparison. Two photos of the same gutter, one full of leaves, one clear. The pair is far stronger evidence than the after photo alone, because it demonstrates a change rather than a state. A verification rule can require both and check that they plausibly show the same location.
Metadata and duplicate checks. Capture timestamp within the campaign window. The same photo not submitted before, by this policyholder or any other, checked with a perceptual hash against the program’s full history. Stock photos of clean gutters are the obvious abuse and they are caught because they recur.
Invoice extraction where a professional was involved. Roof cleaning company, gutter service, boiler engineer. The invoice is read into fields, the tax identifier and date are checked, and the line items are matched to the rewarded service. This is the same pipeline as any receipt program.
Review queue for the rest. Everything the rules cannot settle goes to a person, with the photos, the fields, and the reason side by side.
Designing the reward to match the evidence
Programs that work tend to follow three design rules.
Scale the reward to the strength of the evidence. A professional boiler service with an invoice can carry a larger reward than a homeowner’s gutter photo pair, because the invoice is harder to fake.
Make the rejection reason specific. “We could not see the downpipe opening in your photo” leads to a retake. “Submission rejected” leads to a complaint.
Sample for fraud at the program level, not just the submission level. A policyholder who submits perfect maintenance photos for every category every season is worth a look. Program-level reporting on approvals per person surfaces this.
Why insurers are doing this now
Two reasons. Verification used to require a person looking at every photo, which made a program with tens of thousands of policyholders uneconomic. That constraint has gone. And loyalty platforms have matured to the point where an insurer can run points, tiers, and rewards without building the plumbing, so the verified maintenance action becomes just another earning rule in an existing program.
The result is a program where the insurer’s interest and the policyholder’s finally point the same way. Fewer claims, lower premiums over time, and a reason to open the insurer’s app in October that is not a renewal notice.
If you are designing something like this, book a demo and bring the maintenance actions you would like to reward. We will tell you which ones a photo can carry and what the rules would look like.