Insurance loss prevention rewards: paying policyholders to change their tyres, and verifying that they did
Insurers want fewer claims. A prevention rewards program pays for the winter tyre change or the service visit and verifies each one from a receipt or a photo.
Every motor insurer knows the correlation. Cars on worn or summer tyres in November have more accidents than cars on fresh winter tyres. Cars that get serviced have fewer breakdown and mechanical claims. The insurer pays for the outcome and has almost no influence over the behaviour. Premium discounts for “safe drivers” are backward-looking and blunt.
A prevention rewards program flips this. The insurer pays a small, immediate reward for a specific behaviour that reduces claims: change to winter tyres before the first frost, get the brakes checked, complete the annual service. The policyholder submits proof. The insurer verifies it and pays out, in points, in a premium credit, or in cash. The reward costs less than the claims it prevents, and the insurer gets something it has never had, a regular positive interaction with a customer who otherwise only calls when something has gone wrong.
The whole idea rests on one thing. Verification has to be cheap, fast, and hard to game. Otherwise the program either costs too much to run or pays for tyres that were never changed.
What proof looks like
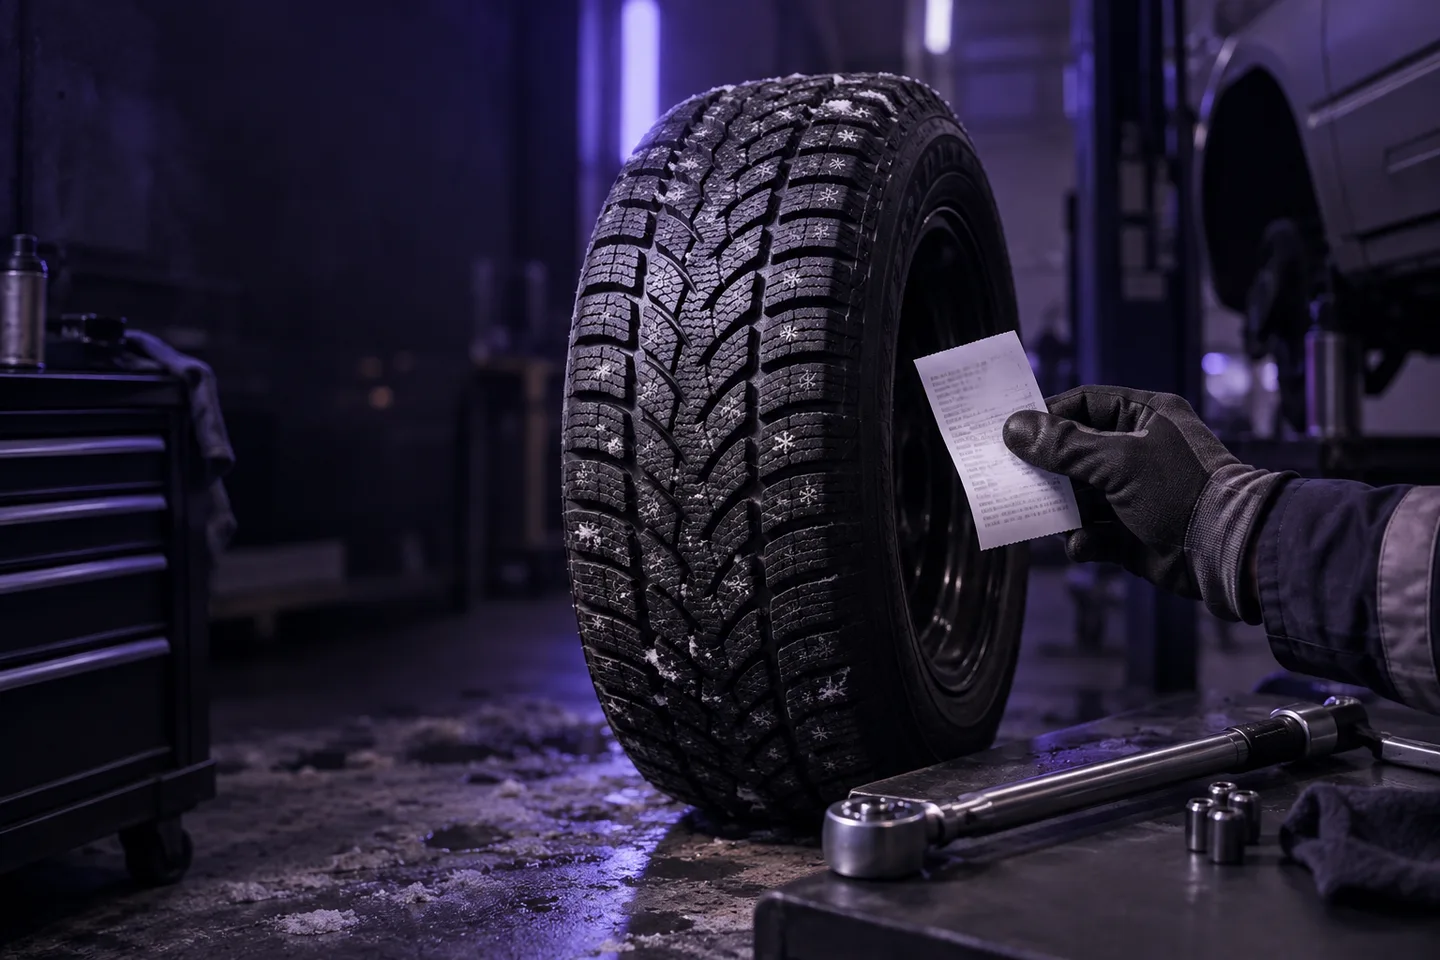
For a tyre change the natural evidence is the invoice or receipt from the tyre service. It carries the garage’s name and tax identifier, the date, the service line items, and often the vehicle registration. Some insurers also ask for a photo of the fitted tyre showing the sidewall markings, which identify a winter tyre by the snowflake symbol.
For a service visit it is the service invoice, sometimes plus the stamped service book. For a brake check, the workshop report.
In every case the proof is a document or a photo, a standard it should meet, and a decision. That is a verification problem, and it is the same one receipt-based promotions solve.
Verifying a tyre change, step by step
Extraction. The invoice photo is read into typed fields: garage name and tax identifier, address, invoice number, date, line items, total, and the vehicle registration if printed. No templates per garage. A hand-written invoice from a rural workshop and a printed one from a national chain go through the same schema-first extraction.
Rules from the program terms. Date inside the campaign window, typically September to the first frost. Line items include a tyre change or winter tyre service. Vehicle registration matches the insured vehicle. Tax identifier belongs to a registered business. Each failed rule returns a reason, which the policyholder sees.
Photo checks, when a photo is required. Yes-or-no questions asked of the tyre photo: is a tyre visible, is a sidewall visible, is the three-peak-mountain snowflake symbol present, is the tread depth indicator visible. Each answer comes with a confidence score. Low confidence goes to a reviewer, not to an automatic rejection.
Duplicate detection. The same invoice submitted for two policies. The same tyre photo from last year. The same garage invoice number appearing twice. A perceptual image hash and an identity fingerprint from tax identifier plus invoice number plus date catch all three, against the whole history of the program.
Review queue. Clean submissions approve and the reward posts to the loyalty platform. Flagged ones land in a queue with the evidence and the reason side by side.
Why this beats the alternatives
Insurers have tried telematics for behavioural pricing and found the uptake poor and the privacy questions loud. They have tried partnerships with garage chains, which reach only the customers who use that chain. They have tried self-declaration, which is worth exactly what it sounds like.
A verified rewards program has none of those problems. It works with any garage. It asks for a photo of a document the customer already has. The data collected is the proof of one specific action, not a continuous stream of location. And it is not a discount that has to be clawed back if the customer lied. It is a reward that is paid only when the evidence passes.
The numbers to model
Before building one of these, an insurer usually models three things. The claims reduction per behaviour, which the actuarial team already has a view on. The reward level needed to move the behaviour, which is a marketing question and often lower than expected because the tyre change was already going to happen and the reward just brings it forward. And the cost of verification per submission, which used to be the deal-breaker because it meant a person reading every invoice.
That third number is the one that has changed. With extraction and rules running on every submission and a person looking only at exceptions, verification cost stops being the constraint on how many behaviours the program can reward.
Beyond tyres
Once the pipeline exists, the list of rewardable behaviours grows. Dashcam installation, verified by receipt and a photo of the mounted unit. Child seat fitting at a certified centre. Advanced driving course completion, verified from the certificate. On the property side, smoke detectors, water leak sensors, gutter clearing, roof inspection, each with its own evidence and its own rules, which is its own article.
The engine does not change. The rules and the evidence do.
If you are an insurer or a loyalty team working with one, book a demo and bring a handful of real garage invoices. We will show you the fields, the verdicts, and the reasons.